Pennsylvania has a big RV and boating culture, and summer brings it to life. But many owners aren’t sure whether their recreational vehicle or watercraft is actually insured the right way. Here’s how to make sure your RV, boat, or jet ski is properly covered before you hit the road or the water.
The first thing to check is registration. If your RV or watercraft is required to be registered or carry a license plate in Pennsylvania, it will need some kind of insurance – that’s usually the stipulation. Where a registration is required, insurance is required to go with it. Beyond that, proper coverage means going to a carrier that will insure the vehicle specifically as a recreational vehicle through their specialty lines.
Some carriers specialize in recreational vehicles – Progressive, for example, is big on RVs. A specialty RV policy can insure not just the vehicle itself, but also include certain contents coverage and trip interruption if something happens while you’re traveling. There are many specialty coverages that come with insuring an RV through a carrier that handles them properly – protections you simply won’t get by trying to force it onto the wrong kind of policy.
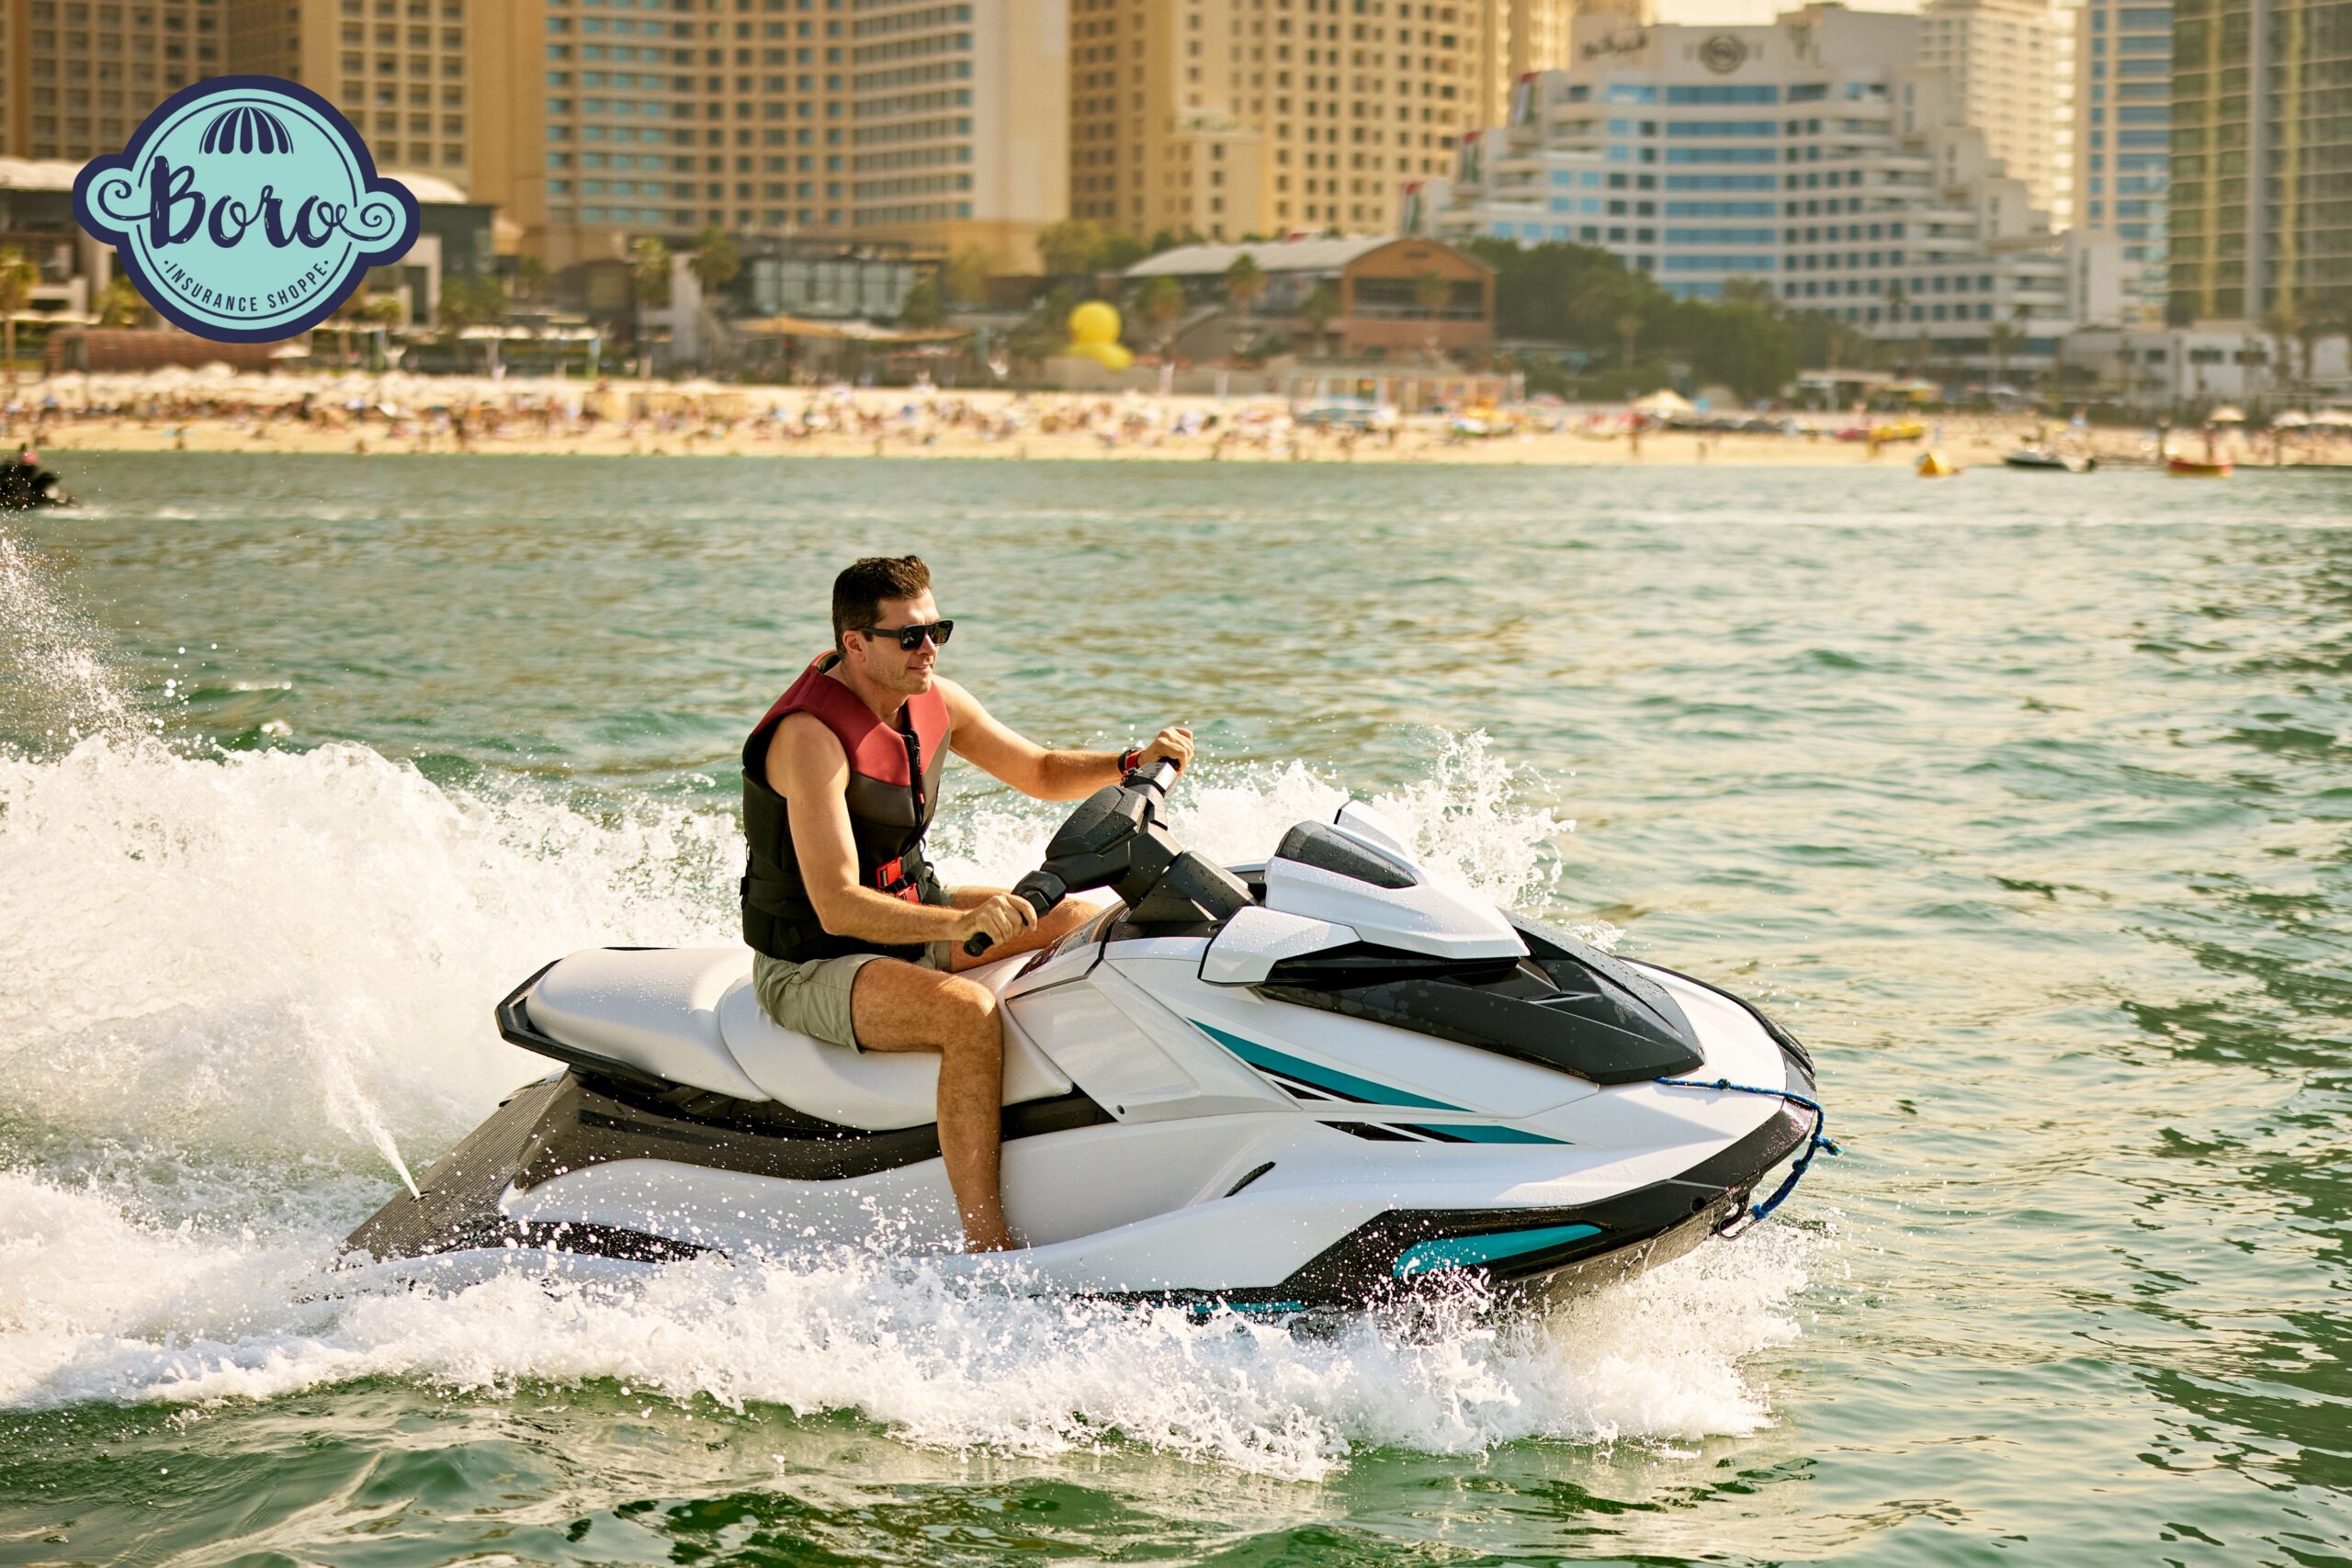
Watercraft work much the same way. Whether it’s a boat or a jet ski, it goes on a dedicated watercraft or boat policy, and it’s protected both while it’s being trailered and while it’s in the water. You can add coverages such as contents coverage for items on the boat, and there are many discounts available – if the boat has equipment like radar, sonar, and ship-to-shore radio, carriers often reward that with various discounts. For these policies, you’ll want to work with a specialty carrier that understands watercraft.
This is one of the most common questions, and the answer surprises people. Typically, a homeowners insurance policy will provide some coverage for a boat if it is under 25 horsepower and is a low-speed, specific-motor type of craft, like a small fishing boat. So your homeowners policy can extend limited coverage to a modest boat.
Once you go over 25 horsepower, or if you have a speedboat or a high-performance “cigarette” boat – it’s no longer treated as a personal-type boat. At that point it’s almost considered a vehicle because of how fast it is, and it has to go on its own dedicated boat policy. If you’re unsure where your craft falls, that’s exactly the kind of detail to confirm with your agent.
It changes everything. If you use your boat or RV for business, you must tell the insurance carrier and confirm whether they even offer coverage for that use – some carriers automatically exclude business use. They’ll also want to know about activities like boat shows, racing events, or exhibitions, any of which could disqualify you with certain carriers. The good news is that there’s a carrier for almost anything; it comes down to cost and coverage. The essential step is full disclosure, so your coverage actually holds up when you need it.
Getting ready for the season? Get in touch with The Boro Insurance Shoppe and we’ll make sure your RV, boat, or watercraft is insured the right way.